Showing posts with label finance. Show all posts

Amortization Calculators and Aggressive Debt Reduction

Lately, I've been thinking about the debt that I have. I have an American Express credit card that I pay off every month - I don't think I've ever paid interest. I also have a sizable privately funded student loan from my undergraduate days (2000-2004) that has been in deferment to this point. Starting this summer, its term is ten years. Finally, I have my motorcycle loan from BMW, which has a five year term.

After all is said and done, I have a fixed amount "above and beyond" what I need for my usual budgeted living expenses (housing, groceries, medical, etc.) that is pretty much discretionary. Currently, I split that evenly between my Roth IRA and the BMW loan. Six weeks from now, my Roth IRA will be 50% funded for 2009. I have decided to shift gears at that point and apply all the "above and beyond" to the motorcycle. When 2010 rolls around, I will re-allocate these discretionary funds so that by the end of the year my Roth will be once again funded 50% and the rest will go toward the motorcycle. On top of this, "extra" paychecks (I get paid every Thursday and budget monthly so every 3 months there is a surplus) will be contributed 50% toward loan repayment. When the motorcycle is paid off, I'll simply apply the payments to my student loan.

Using a loan amortization schedule I found here, I calculated that this tactic will pay my bike off on May 14, 2010 (one year minus one day after I bought it) and my student loan will be paid off in June of 2012. At that point, I will step my Roth IRA back up to 100% annually. I'll probably increase my 403(b) contribution at work as well.

I don't feel like I will be missing out on anything huge by reducing my Roth IRA contributions - I will still be contributing and I have been contributing 8% of my pre-tax income (I don't remember exactly why I chose this number but I'm sure there was some logic to it) to my 403(b) since I started working full-time in January of 2005. In addition, my employer contributes 8% to a 401(a) in addition to my paycheck. To me, the peace of mind of having the loans paid off is worth the opportunity cost.

Fiscal Frivolity

It seems May has been a month of budget overages. I haven't run the sums yet, but I did make some big purchases that I hadn't quite expected:

  • A replacement projector bulb
  • A new motorcycle
  • Appropriate safety equipment for said motorcycle
  • A new mattress set to replace my 4th-hand set

The above purchases were made with funds I had saved ahead of time or financed at relatively good rates with no prepayment penalties (the motorcycle). I did better on the mattress than I could have - I had considered getting a new frame and switching to a platform bed but it just made more sense to get a nicer mattress set - which I comparison shopped for at 5 places and got a good deal on the one I eventually bought (1/2 MSRP). I don't regret any of the big purchases above, but I have also been eating out quite a bit lately. Maybe it's because I don't feel well and don't feel like fixing food at home. Or maybe it's that I know my budget is way out of whack and I just figure I'll start over in June. It's probably also partially my tendency to keep spending when I start. At any rate, the exact numbers will be known later this week when I get everything transferred to my spreadsheet and summed.

And I will start over in June - with fresh goals and fresh ideas. One of my goals for the month is to clean out my closet, my room, and my workshop of things that can be sold or donated which will both reduce clutter and either build my savings or pay off part of the bike.

Two Reviews: Ben Folds Concert and Star Trek

I guess this isn't STRICTLY a financial post, but they're both things of an entertainment nature that I spent money on after some consideration so it flies, albeit loosely.

Wednesday night (5/20) I went to a Ben Folds concert at the Hollywood Palladium. I took a friend who is a big Ben Folds fan for a belated birthday celebration. The venue was really cool. The Palladium is an art deco style relatively intimate venue with standing room (dance floor, balcony, VIP balcony) for about 4,000 people. The acoustics were excellent - we stood on the balcony about 45 degrees of the center of the stage. The concert itself was great. Four acapella groups opened with Ben Folds covers and the audience voted for their favorite by applause. Ben himself is an awesome pianist and singer. The band was also quite good - drum set drummer, miscellaneous percussionist, keyboardist, and bassist. I knew probably about half the songs - Ben did a fair bit of his newer stuff. For the encore, he brought out Josh Groban to sing for the first song and then did a Dr. Dre cover for a final closer. Final verdict: a great concert at a great venue - well worth it.

Thursday night (5/21) I went to see Star Trek in IMAX at The Bridge with my brothers and a couple friends. The IMAX experience is never disappointing and the film itself was quite good. The characters were well written and acted, and the first time Kirk plops down in the captain's chair it screams young Shatner. It's cool meet all the familiar people from The Original Series as young men and women. I don't want to give away any plot for those who haven't seen it, but I can heartily recommend it for experienced Trekkies and newbies alike.

A slight change of financial plans...

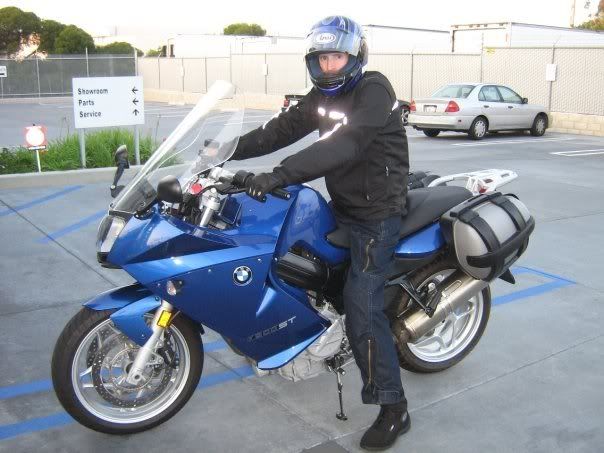
After a year of the Silverwing being non-operable and a week of consideration and logistics, I purchased a new motorcycle - a 2008 BMW F800ST (slightly used with only 2300 miles):

Although this will set back the repayment of my student loan by a couple years, I feel it was a good purchase - especially for my emotional health (which certainly impacts other health). I am still maxing my Roth IRA and contributing a healthy amount to my 403(b) at work. The bike will also reduce the amount I am paying for gas since it gets awesome mileage and will prolong the useful life of the Corolla since I'll only be using it occasionally. In addition, I was able to get full-coverage insurance on the BMW along with liability for the Silverwing and the scooter for only about $100 more annually than I had been paying for liability for the other two.

I'm very excited since I've missed motorcycling quite a lot - I didn't realize how much until I got back on this weekend. I'm already planning to take some weekend trips and will be sure to take the camera with.

"Extended Warranty" Ridiculousness

Normally, I am not a person to purchase "add-ons" like extended warranties, service plans, cell phone insurance and the like. Most small electronics depreciate rapidly and will outlast the terms (even if just barely) and I take excellent care of what I own.

However, a couple years ago I purchased a projector from Broadway Photo. I was called soon after my online purchase by a sales representative attempting to sell me a "bulb replacement plan." DLP projectors and televisions use a very bright light bulb that bounces off tiny mirrors and shines through a color wheel to produce the images. These bulbs cost $300-$400 apiece and don't get cheaper as the projector ages. The "bulb replacement plan" was sold by a third party company called RepairTech, cost $200 and allowed for free replacement of up to two bulbs within three years for whatever reason, including end-of-life (3000 hours for my particular projector). After questioning the sales rep about all types of scenarios, I felt assured that it was worth it to pay $200 for up to $800 worth of bulbs.

Well, after 21 months (coincidentally, the gestation period of an elephant is the same period of time), the bulb finally reached end-of-life so I set the replacement process in action. Much to my chagrin, the toll-free number was disconnected and the website was blank. Some Googling brought me to discover that RepairTech had gone out of business sometime in the summer of 2008. People with extended warranties were finding it impossible to get them honored and had been struggling for months in some cases.

I also did some Googling on Broadway Photo and discovered that they too had some customer satisfaction issues. I suspected this when I had pulled out my invoice and saw that they had adjusted the price of the projector upward by $200 and listed the warranty as $0.

My last course of action was to call American Express since that is the card on which I originally bought the projector. While they offer an additional one year of coverage beyond the manufacturer's warranty, they will not extend third party warranties.

Since I was not interested in struggling for months with no probable results (and more importantly, no home theater), I finally ended up just purchasing an OEM bulb for $335. Generic are available but more Googling indicated that not only is build quality typically very low, the light output and lifetime are quite variable and nearly always considerably less than OEM.

I'm still not sure whether I can definitively say it was a bad idea to purchase the "bulb replacement plan" when I did. In retrospect, it was obviously the wrong choice in this particular instance thanks to all the circumstances involved. I do know I won't buy any third-party extended warranties in the future. $16 saved a month would pay for the bulb in full. My brother Daniel came up with the clever idea to have a change box in the theater and throw a dime in every time the projector is on for an hour. I think this is a great idea.

April budget summary

Only two overages this month:

  • Vehicle: I decided to get my front seats upholstered, to the tune of $600 (half of which I paid as a deposit in April, the rest of which I will pay tomorrow). I have been planning to do this for some time and simply hadn't explicitly placed it in the budget. The balance will be included in May's budget.
  • Medical: I had a filling that came out in March, so that obviously had to be taken care of. Insurance and billing took about a month to catch up.

Groceries for The Maker's Diet are more expensive than I had been eating. I spent more than the last couple months but my grocery/entertainment category still came out about $20 under budgeted.

I definitely need to set up a flexible spending account next year - all the medical expenses could be pre-tax if I had taken the time to do so.

March budget update

Well, this was kind of an insane month budget-wise.

I had unexpected expenses in both needs and wants. My car and motorcycle insurance as well as my motorcycle registration all came due within the last couple weeks. I also spent a decent sum over budget on my car as well - like I mentioned a couple weeks ago, I finally got around to installing my power locks and windows and needed a fair number of parts I thought I already had. I should be able to recoup some of this in the future by selling off everything I didn't end up using.

I was wise did finally add a category for unexpected this month, complete with a $200 allotment. I bought a fancy new (to me) smartphone and some other stuff and this category ended up overspent by about the same amount my grocery category was underspent. I decided to do some manipulation and moved the phone to grocery (this also includes toys and entertainment) since it was more of a gadget expense than a necessary emergency or unexpected expense. Now they're both within $10-15 of estimated/budgeted. Along with my new phone, I decided to get a data plan so that will add $30 a month.

I joined 24 Hour Fitness, which cost $60 up front (no joining fee but you must pay first and last month's membership upfront) and will cost $30 a month but will hopefully pay off in health benefits. After finally getting my chiropractic billing issues straightened out, I decided to cut my chiropractic back to every other week instead of every week. I'll just make sure to stretch more. I do know that regular exercise does help my back remain limber.

I set up some automatic savings plans for my Roth IRA through Scottrade (to be fully funded by December 31), payments toward principal on my student loan, and a fund for future car insurance and registration expenses - both of the latter through ING Direct where I opened sub-accounts specifically for those purposes.

I also received my federal income tax refund, which was sizable. I immediately transferred most of it to my ING Direct general savings account. I'm not going to frivolously spend the rest - I left it in my checking account as a cushion since the car insurance wiped that out.

My goal for April is to have everything come out at or under budget (except savings). We'll see how I do. I still do have that unexpected category for contingencies.

January Budget Report

Overall, I did well. I tracked every cent I spent the entire month, including mundane stuff like soda from the snack fridge and parking meters. Without going into boring detail, I managed my expenditures well. I did go over in grocery, entertainment, and eating out (all 3 are the same category) and had a couple unexpected expenses - namely a new microwave and the registration fee for the Navigator prayer retreat. My chiropractic was much higher than projected since I had several outstanding visits.

The chiropractic and unexpected were necessary and worthwhile expenditures so I don't feel too badly about that. My food and fun budget was $465 ($15 per day) and my excess for the month was $70. I can look through the month's expense list and see a handful of things I could knock off - I purchased a video game on impulse on the first of the month that was about $45 of that and taking a salad from home for lunch costs about half what it does to buy from the salad bar (and my salads are fresher and contain exactly what I want). Despite my excess expenditures, I did manage to contribute a significant chunk to my Roth IRA for tax year 2008, which brought my yearly contribution to half the allowed limit.

I have already learned the value of tracking expenditures daily and established a habit of doing so - when it's at the forefront of your mind, it's not difficult to have a pb&j sandwich instead of going out for mediocre fast food or to pass on junk food at the supermarket. I've also learned it's important to be flexible - it may be more important to participate in an activity or have lunch with friends than to save another few bucks.

One cost associated with this new mode of operation may end up being one of my dress shirts! I often jot down what I spend at work on a post-it note and stick it in my shirt pocket. Last time I washed my shirts, I overlooked one of these and it bled yellow onto my blue and white striped shirt. I hope I can get it out - I did wash it cold but also dried it.

My financial goals for the year include funding my Roth completely for 2008 and 2009 (2008 may be funded until April 2009), starting an emergency fund, and beginning to make principal payments on my remaining undergraduate student loan (which was in deferment until I earned my Master's). The balance of emergency fund/savings account to student loan principal remains to be determined.